
Key Takeaways
- Choose coverage based on the services you are most likely to use.
- Premiums are only one part of the yearly cost of dental care.
- Check deductibles, annual maximums, exclusions, and frequency limits.
- Confirm that your dentist and nearby specialists participate before enrolling.
- For family coverage, review each person’s needs separately.
Choosing dental coverage starts with a practical question: what care are you most likely to need in the next year? A plan that works well for routine cleanings may offer limited help with crowns, root canals, dentures, or orthodontic treatment. Comparing options through the lens of your dental history can lead to a more useful choice than selecting a policy based solely on the premium. Reviewing covered services alongside your expected dental needs can help you better understand the value of each option.
Provider access matters just as much as the benefit schedule. For example, people who want the flexibility to continue seeing a familiar dentist can check whether that office participates in the Delta Dental PPO network and confirm how costs differ between in-network and out-of-network care. Checking network participation before scheduling care can help you anticipate potential out-of-pocket expenses.
Start With a Clear Picture of Your Oral Health
Begin with your recent dental visits. Think about whether your care has mostly involved exams and cleanings, or whether you have needed fillings, periodontal treatment, extractions, root canals, or replacement teeth. If your dentist has recommended treatment that has not yet been completed, include it in your comparison.
Your past care does not predict every future need, but it provides a more realistic starting point than price alone. If you are unsure what may be needed soon, ask your dentist which services are likely to be needed in the coming year and whether a pre-treatment estimate would be appropriate for planned work.
Sort Care Into Common Benefit Categories
Dental plans often organize covered services into categories. The names and details vary by policy, so always read the plan documents carefully.
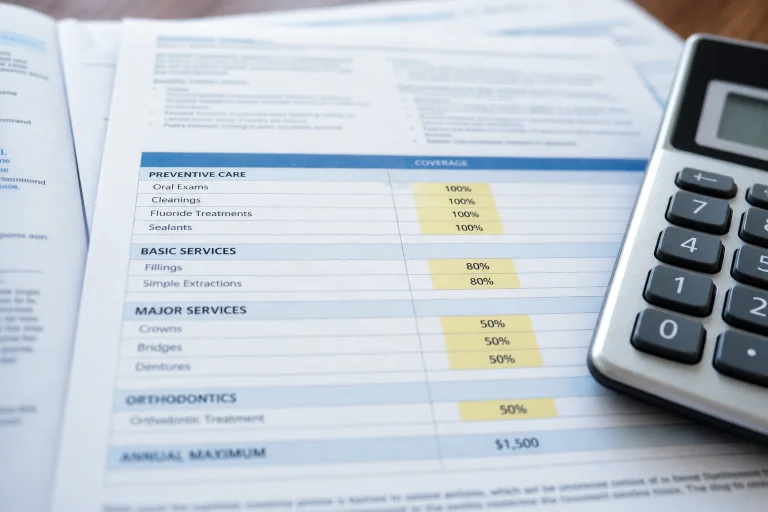
- Preventive care: Often includes exams, cleanings, and diagnostic X-rays.
- Basic care: May include fillings, simple extractions, and certain gum treatments.
- Major care: Can include crowns, bridges, dentures, root canals, implants, or more complex oral surgery, depending on the policy.
- Specialty care: May involve orthodontics, periodontal treatment, or services provided by an oral surgeon.
Coverage can vary significantly between dental insurance plans. Since benefit designs differ, a procedure classified as basic under one policy may have different limits and cost-sharing requirements compared to another.
Match Coverage to Likely Care Needs
Routine-care households
If you generally need only preventive visits, prioritize access to convenient in-network dentists, covered cleanings and exams, and any frequency limits. A lower premium may be reasonable if the policy still provides usable preventive benefits and your preferred office participates.
People with recurring restorative needs
If you have a history of cavities or have been advised that older fillings need attention, look closely at the plan’s share of basic services. Check whether the deductible applies and whether the plan uses a fixed copayment, a percentage of the allowed amount, or another payment structure.
People are anticipating major work
When a crown, root canal, bridge, denture, implant, or oral surgery may be needed, the annual benefit maximum becomes especially important. A plan can pay a percentage of covered major care while still leaving a substantial balance, particularly after the maximum is reached.
Parents and older adults
Parents should evaluate each child’s provider, anticipated preventive care, potential orthodontic needs, and the plan’s age or lifetime limits for braces. Older adults may want to pay extra attention to coverage for dentures, periodontal services, oral surgery, and specialists.
Compare the Numbers That Shape Total Cost
Put these features side by side for every plan you are considering:
- The monthly premium and the total premium for a full year.
- The individual and family deductible.
- The percentage or fixed amount the plan pays for each service category.
- The annual benefit maximum per covered person.
- Potential charges for out-of-network treatment.
Estimate costs under two situations. First, price a low-care year with routine preventive visits. Then price a higher-care year that includes a likely filling, crown, or other anticipated procedure. Add premiums, deductibles, and your estimated share of treatment. This approach makes it easier to see whether a low-premium plan may create higher costs when care is actually needed.
Check Dentists and Specialists Before You Enroll
Use the plan directory as a starting point, then call the dental office. Ask whether the dentist participates in the specific plan, accepts new patients, and can provide the care you expect to need. If you see a periodontist, orthodontist, endodontist, or oral surgeon, verify nearby access to specialty care as well.
Do not assume that a dentist who accepts one product from an insurer accepts every product offered by that insurer. A plan with a lower premium can become less attractive if it requires you to switch providers or results in higher out-of-network costs for common care.
Read Beyond the Benefit Summary
A short comparison chart is useful, but it rarely includes every condition that affects payment. Read the policy, certificate, or evidence of coverage and look for:
- Covered services and excluded procedures.
- Limits on exams, cleanings, X-rays, or periodontal maintenance.
- Replacement intervals for crowns, bridges, and dentures.
- Pre-treatment estimate, claim, or referral requirements.
Insurance can help manage eligible dental expenses, but it does not replace preventive habits or professional care. The professional and self-care steps that support oral health include regular dental visits, brushing twice daily, flossing daily, and limiting foods and drinks high in added sugar.
Review Family Needs One Person at a Time
One family member’s needs should not determine the entire household’s choice. Create a simple list for every person that includes age, regular services, current dentist or specialist, expected treatment, preferred provider location, and likely spending over the next year. Then compare those needs against each plan’s network and benefits.
Simple Plan Comparison Checklist
- Does the policy cover the services you are most likely to need?
- Is your preferred dentist in the network?
- Are convenient specialists available?
- What are the deductible and annual maximum?
- How much does the plan pay for preventive, basic, and major services?
- Are there frequency limits or exclusions?
- How are emergency and out-of-network visits handled?
- Does the estimated yearly total fit your budget?
Common Mistakes to Avoid
Avoid choosing solely based on premium, assuming all dentists participate, overlooking the annual maximum, or relying solely on marketing summaries. Also review coverage at renewal or whenever a family member changes dentists, begins orthodontic care, develops gum concerns, or receives a treatment recommendation.
Conclusion
The best dental insurance plan is not automatically the least expensive option. It is the plan that aligns with your likely care needs, provides practical access to providers, and offers clear protection within your budget. Compare the full cost, network, benefit limits, and policy details together before making a decision.
