
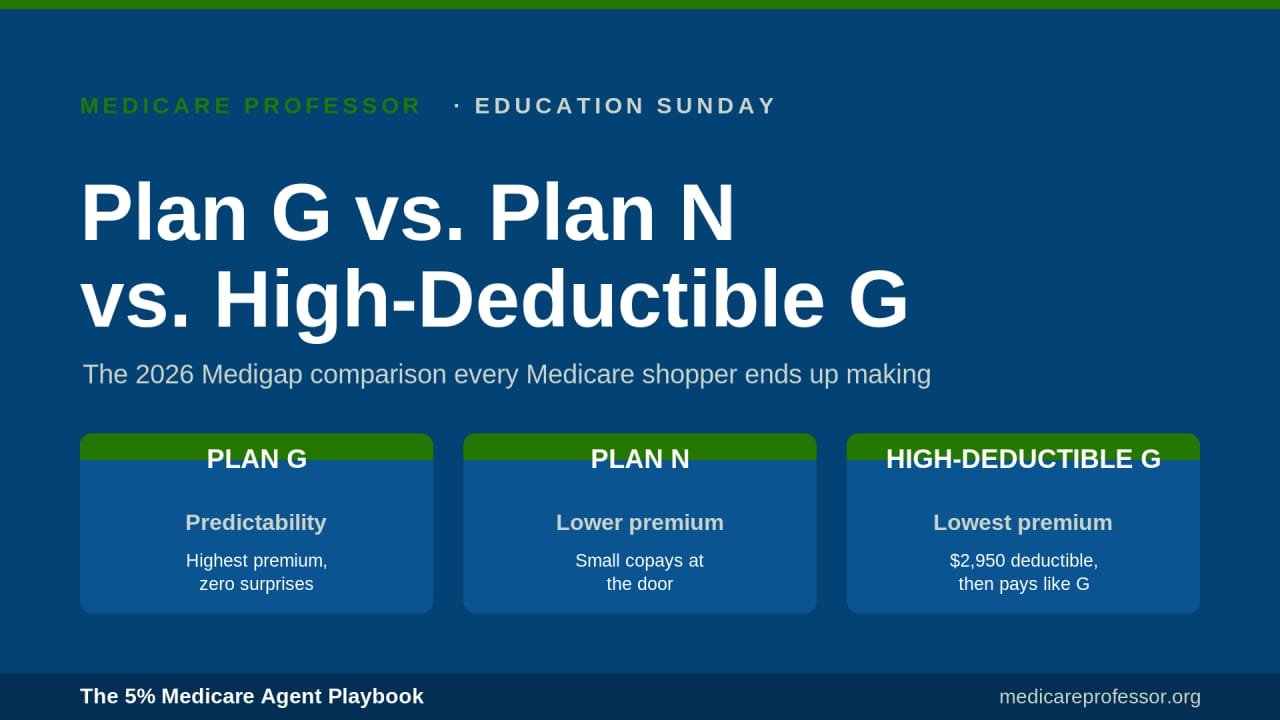
Choosing a Medicare Supplement plan often feels more complicated than it needs to be. With so many letter-named options available, most people simply want a straight answer about which plan fits their situation. This guide answers the most common questions people ask when comparing their choices, using a clear, conversational format designed to make the decision easier. Medicare Plan G tends to suit people who want robust coverage without constantly worrying about denied claims or gaps in protection. If you prefer predictability over flexibility, and you would rather pay a steady monthly premium than face unpredictable medical bills, this plan is often the strongest fit.
Rather than listing dry facts, this article walks through real-world scenarios: the cautious retiree who wants predictable costs, the frequent traveler who needs broad coverage, and the budget-conscious shopper willing to take on more risk for lower monthly payments. By the end, you should have a much clearer sense of where you fit.
Who is the ideal candidate for Medicare Plan G?
This plan particularly appeals to retirees managing chronic conditions, frequent doctor visits, or ongoing prescriptions tied to medical treatment. Since nearly all out-of-pocket costs are covered except the annual Part B deductible, people who dislike surprises in their healthcare spending tend to feel most comfortable with this option. It also suits those who want long-term simplicity, since the structure of the plan rarely changes year to year.
How does Plan N compare for someone who wants lower premiums?
Plan N can be a smart choice for individuals who are generally healthy, don’t visit specialists often, and are comfortable with small, predictable copays in exchange for a lower monthly premium. Unlike more comprehensive plans, Plan N requires minor copays for certain office visits and emergency room visits, plus it does not cover Part B excess charges in the same way.
This plan is well suited to someone who wants a balance between cost savings and dependable coverage. If you’re the type of person who doesn’t mind budgeting for small, occasional out-of-pocket costs in return for meaningfully lower premiums, Plan N might make more financial sense long term. It’s especially appealing to those in states where providers rarely charge excess fees, since that concern becomes far less relevant.
Is Plan F still a good option for new Medicare enrollees?
Plan F is only available to those who were eligible for Medicare before a certain cutoff date, meaning it’s not an option for everyone. For individuals who already have Plan F, or who became eligible early enough to qualify, it remains one of the most comprehensive supplement plans available, covering essentially all gaps left by Original Medicare, including the Part B deductible.
If you already hold Plan F and are comparing it to Plan G, the decision usually comes down to whether the extra comprehensiveness is worth a typically higher premium. Many people who are already enrolled choose to stay, especially if they value having zero out-of-pocket exposure. However, new enrollees exploring supplement plans for the first time should understand that Plan F simply isn’t part of their available choices, which often naturally leads them toward Plan G instead.
When does Plan A make sense instead of Plan G?
Plan A is the most basic Medicare Supplement option, covering core benefits only, such as Part A and Part B coinsurance, the first three pints of blood, and hospice care coinsurance. It does not include coverage for the Part B deductible, skilled nursing coinsurance, or foreign travel emergencies.
This plan can make sense for someone with a tight monthly budget, minimal healthcare needs, and a strong emergency fund they’re comfortable using instead of paying higher premiums. It may also appeal to people who are confident in their current health and want the lowest possible monthly cost, accepting a higher amount of personal financial risk in return. For most people balancing cost and protection, however, Plan A tends to leave more exposure than many are comfortable with compared to Plan G.
Who benefits most from the High-Deductible Plan G option?
The High-Deductible version of Medicare Plan G offers the same categories of coverage as standard Plan G, but requires you to pay a set deductible out-of-pocket before the plan begins covering costs. Once that deductible is met, coverage functions the same way as the standard version.
This option tends to suit individuals who are in good health, don’t anticipate frequent medical expenses, and would rather pay a much lower monthly premium while keeping a safety net in place for larger, unexpected costs. It’s a strategic choice for people who have enough savings to comfortably cover the deductible if needed, but who want to avoid overpaying monthly for coverage they may not use. If your goal is minimizing monthly spending while still having comprehensive protection available when it matters most, the high-deductible option can offer real value.
How should someone with frequent travel plans choose between these options?
For individuals who travel often, whether domestically or internationally, foreign travel emergency coverage becomes an important factor. Plans G, N, and F all include this benefit, while Plan A does not. If international travel is a regular part of your lifestyle, prioritizing a plan that includes this protection can prevent major financial exposure while abroad.
Among the travel-friendly options, the decision generally comes down to your comfort with cost versus comprehensiveness. Someone who travels extensively but also wants predictable costs while away from home may lean toward standard Plan G, since it minimizes unexpected costs in unfamiliar healthcare systems. Someone more budget-conscious but still wanting travel protection may find Plan N to be a reasonable middle ground.
What role does risk tolerance play in choosing a Medicare Supplement plan?
Risk tolerance is one of the most overlooked factors in this decision, yet it shapes which plan will feel right long term. People with low risk tolerance, who want to avoid financial surprises altogether, generally feel most comfortable with standard Plan G or Plan F if they’re eligible. These plans minimize unpredictability by covering almost all expenses beyond the monthly premium.
On the other hand, people with higher risk tolerance, who are comfortable absorbing occasional costs in exchange for lower premiums, often find Plan N or the High-Deductible Plan G option more appealing. These choices require accepting some financial unpredictability, but they reward that acceptance with meaningfully reduced monthly payments. Understanding your own comfort level with financial uncertainty is often just as important as comparing the plans themselves.
How does budget style affect which plan is the right fit?
Some people prefer a “pay more now, worry less later” approach, which naturally points toward standard Plan G or Plan F. Others prefer a “pay less now, handle costs as they come” approach, which tends to favor Plan N, Plan A, or the High-Deductible Plan G option.
Neither approach is inherently better; it depends entirely on personal preference, financial stability, and comfort with variability. Someone on a fixed income who values consistency might prioritize predictable premiums over potential savings. Meanwhile, someone with flexible savings and a preference for lower monthly costs might feel perfectly comfortable absorbing occasional out-of-pocket expenses.
What should someone with ongoing health needs prioritize when comparing plans?
If you manage a chronic condition, see specialists regularly, or require frequent prescriptions and treatments, minimizing unpredictable costs usually matters more than minimizing monthly premiums. In these situations, standard Plan G tends to be the most practical option, since it covers nearly every gap left by Original Medicare after the annual deductible is met.
This becomes especially relevant for individuals managing multiple health conditions simultaneously, where frequent provider visits and tests could otherwise lead to accumulating costs under more limited plans. Prioritizing comprehensive coverage in these cases often provides better long-term financial stability, even if the monthly premium is higher.
Is it ever worth switching from one plan to another later in life?
Switching plans later in life is possible, but it typically requires medical underwriting unless you qualify for a guaranteed issue right. This means your health history could affect your ability to switch, or the premium you’d be offered if you do.
For this reason, many people choose to think carefully about their current and future health needs before selecting a plan, rather than assuming they can easily switch later. If you anticipate your health needs may increase over time, starting with a more comprehensive plan like standard Plan G may prevent complications down the road. Those confident in their long-term health stability may feel more comfortable starting with a lower-premium option, knowing they’ve already accounted for the associated risks.
Making a confident, personalized decision
Choosing between Medicare Supplement plans ultimately comes down to understanding your own health patterns, financial comfort level, and lifestyle needs. There’s no universally “correct” choice, only the option that aligns best with how you want to manage healthcare costs and uncertainty.
Take time to reflect on your current health, anticipated medical needs, travel habits, and how much financial unpredictability you’re willing to accept. Once those priorities are clear, selecting the right plan becomes a far more straightforward process.
